OurTop10 Research · November 2026 · Survey of 1,018 Australians
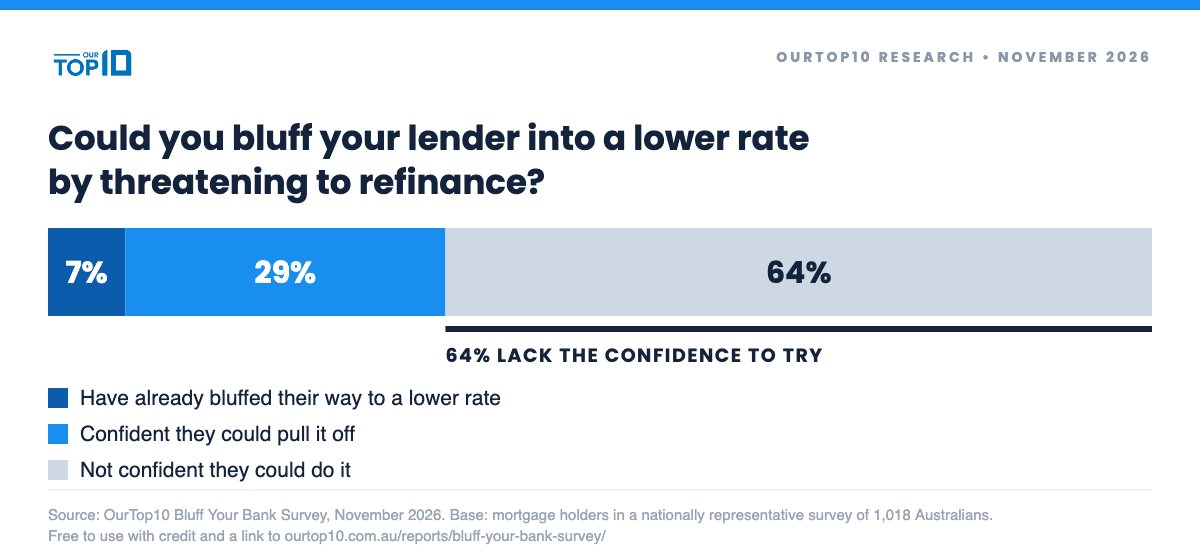
Most Australian borrowers may be leaving money on the table by holding back from playing hardball with their lender. New OurTop10 research shows nearly two in three mortgage holders (64%) lack the confidence to bluff their way to a lower interest rate by threatening to refinance.
Most mortgage holders won’t risk the bluff
The nationally representative survey found that nearly two-thirds of mortgage holders (64%) say they lack the confidence to bluff their way to a lower interest rate with their current lender by threatening to refinance.
Only 29% backed themselves to pull it off, while 7% said they’d already bluffed their way to a lower mortgage rate.
Millennials most likely to back themselves at the bargaining table
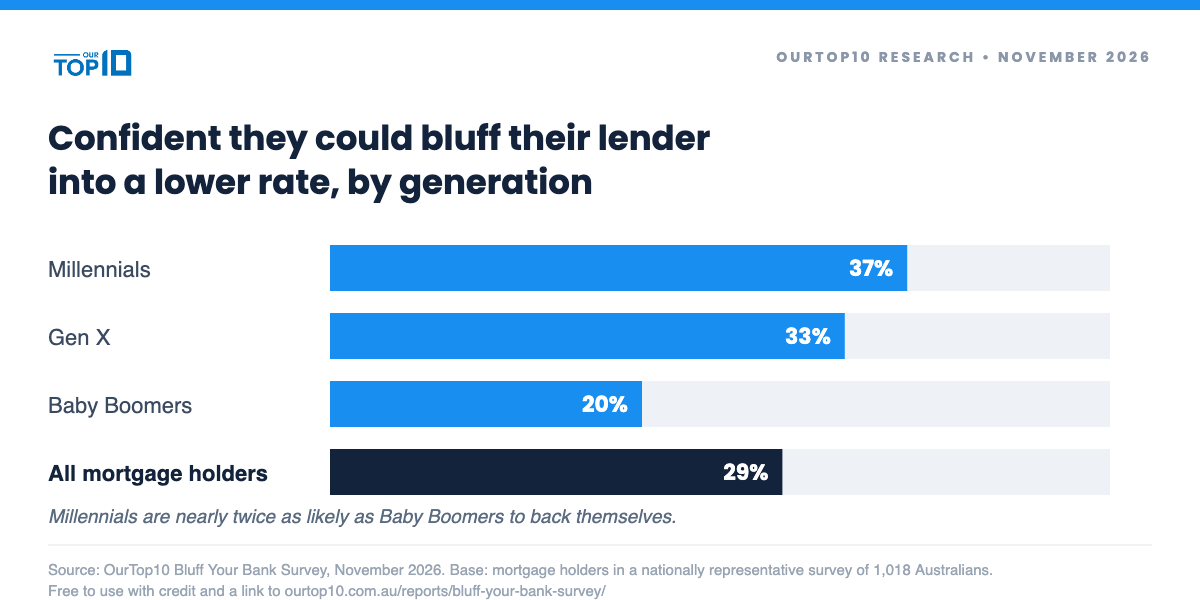
Millennials are the boldest, with 37% believing they could secure a lower interest rate by threatening to take their business elsewhere. That’s nearly double the share of Baby Boomers (20%). Gen X sits just behind Millennials at 33%.
Baby Boomers are the most hesitant of any generation, with seven in 10 (70%) saying they wouldn’t feel confident trying the tactic. That compares with 61% of Gen X and 56% of Millennials.
What OurTop10 says
Mansour Soltani, Head of Research at OurTop10, says younger borrowers are more likely to have seen the tactic in action online.
“Younger borrowers are far more exposed to money tips on social media. Scroll through TikTok or Instagram and you’ll find hundreds of videos showing how people have talked their bank into a lower rate or cashback. Seeing strangers online pull it off makes them more willing to try it at home, so to speak.”
A better deal could be a bluff away
Mr Soltani says borrowers don’t need to refinance to get a better deal.
“The reality is that refinancing doesn’t always stack up once you factor in switching costs like discharge fees, government fees and your time. As a rule of thumb, unless the difference is at least 0.25 percentage points, you’re often better off staying put, unless you’re planning to lock in a fixed rate. But that doesn’t mean you can’t use the threat of leaving as leverage.”
“That’s where it pays to have a competitor’s rate up your sleeve. Just make sure it’s a like-for-like comparison. If you’re on a package loan with an offset, bring a rate for a comparable package and factor in any fees.”
“If you’re getting nowhere, take the bull by the horns. Say you’re prepared to leave and ask for a discharge form. You don’t have to lodge it, but asking for one usually gets you through to the retention team. Their job is to keep your business, so ask them what they’re prepared to put on the table.”
“I’ve seen this work well for plenty of borrowers who can sound confident over the phone. Even a 0.10 percentage point reduction is worth it when all it costs you is 10 minutes of your time. Plus, the major banks are being pretty aggressive about keeping customers at the moment. Lending volumes have slowed since the Federal Budget changes, so they’ve got good reason to hang on to the borrowers they already have. In some cases, they’ll match a competitor’s rate or even throw in a quiet cashback to keep you. If you’ve got a loan over $750,000 or multiple loans with the same bank, you may have more room to push for a better deal.”
Mansour Soltani, Head of Research, OurTop10
The $33,000 phone call
A borrower with a $700,000 loan over 25 years who negotiates their rate down by 0.25 percentage points, from 6.70% to 6.45%, would cut their monthly repayments from $4,814 to $4,705.
That’s a saving of $109.70 a month, or $1,316 a year. Over the life of the loan, assuming rates otherwise stay the same, it adds up to $32,910 in interest saved.
Want to know if your rate is worth a phone call? Grade your home loan rate against what lenders charge today.
Methodology
OurTop10 commissioned the survey from PureProfile, with a nationally representative sample of 1,018 Australians aged 18+, stratified by gender, age and location. Responses were anonymous. Findings on this page are for respondents with a mortgage.
Using this research
You can use this report and its charts. If you use this information, please credit OurTop10 and link to https://ourtop10.com.au/reports/bluff-your-bank-survey/
Related OurTop10 research and tools
- Rate My Mortgage: grade your home loan rate A to F against what lenders charge today.
- Mortgage Stress Report: which postcodes have the most households under mortgage pressure, updated every quarter.
- OurTop10 Rate Prediction Index: what economists and the market expect from the RBA at its next meeting.
- Negative Gearing & CGT Election Survey: how many Australians would vote to reverse the 2026 property tax changes.
Media contact
Mansour Soltani, Head of Research, OurTop10
Phone: 0405 500 981
Email: [email protected]
Downloads
Available to download. If you use it, please credit OurTop10 and link to this page.